Does Homeowners Insurance Cover a Slab Leak?
Most Missouri City slab leak claims hinge on one question: did the pipe fail suddenly or wear out slowly? Here's how insurance really handles it.
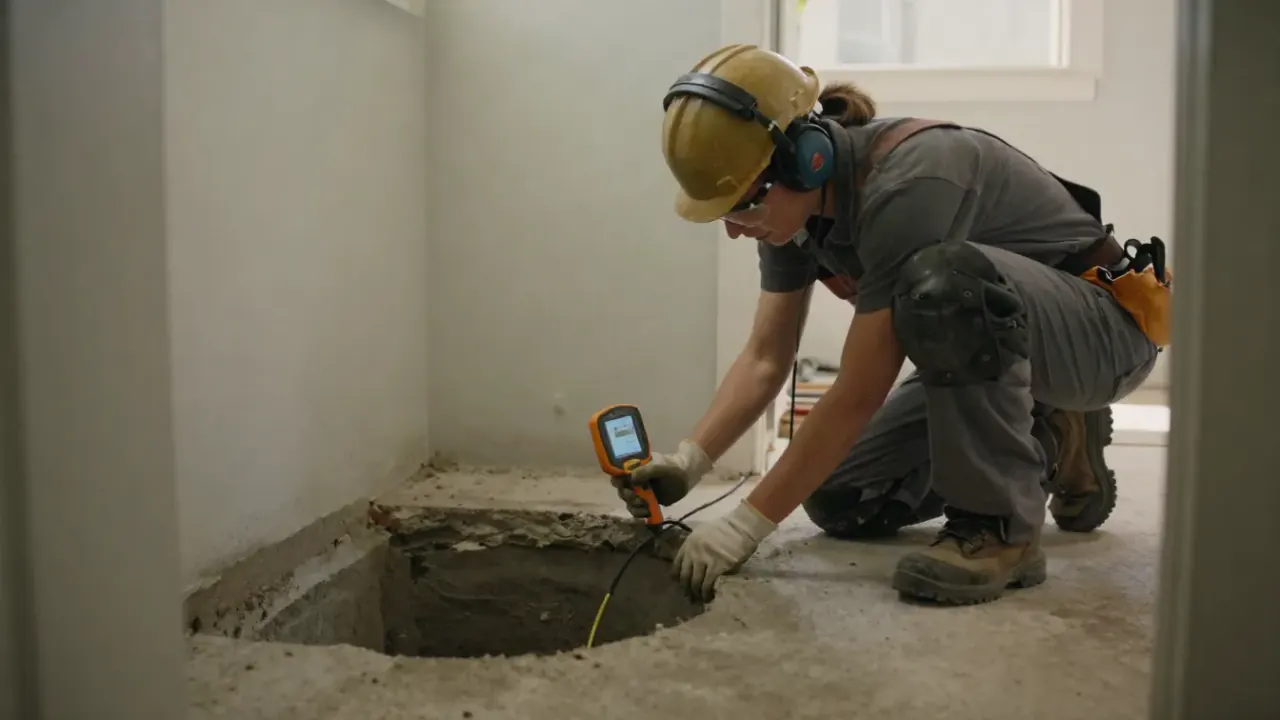
Does homeowners insurance cover a slab leak? Usually, no - not the pipe repair itself. Most Texas policies exclude the pipe because it failed from age, corrosion, or wear and tear, which insurers classify as a maintenance issue. What they often do cover is the resulting water damage to your floors, walls, and personal belongings, provided the loss was sudden and accidental.
That distinction drives every slab leak claim we help Missouri City homeowners sort through. Below, we break down what's typically covered, what isn't, how to file a claim the right way, and the mistakes that get claims denied.
The Short Answer: It Depends on the Cause
Slab leak insurance coverage in Missouri City TX hinges on whether the pipe failure was sudden or gradual. A sudden, accidental event - like a pipe bursting from a pressure spike or a nail driven through a line during a remodel - has a much stronger chance of being covered. A pinhole leak that's been weeping under your foundation for six months is almost always classified as gradual deterioration, and that's excluded.
Here's the definitional piece: does homeowners insurance cover a slab leak is a coverage question that asks whether your policy will pay for the pipe repair, the water damage, or both. In practice, the answer splits - the pipe itself is usually your responsibility, while the damage it caused may be reimbursable.
We see this play out constantly in older Missouri City neighborhoods. A homeowner in Quail Valley Slab Leak Repair with a 1970s copper line that finally gave out will hear "wear and tear" from the adjuster. The same homeowner whose line was nicked by a contractor last week has a legitimate sudden-damage claim.
What Texas Homeowners Policies Typically Cover
Texas HO-3 and HO-5 policies - the standard forms most Missouri City homeowners carry - usually cover the water damage a slab leak causes, not the pipe that leaked. That means the soaked hardwood, the ruined baseboards, the warped cabinets, and sometimes the cost of tearing out and replacing the slab to reach the damaged area.
Here's what's commonly reimbursable when the cause qualifies:
- Water damage to flooring - hardwood, laminate, tile, and carpet that got soaked.
- Wall and baseboard damage - drywall, paint, and trim affected by wicking moisture.
- Personal property - furniture, rugs, and electronics damaged by the water.
- Access costs - breaking out and restoring the slab to reach the leak, in many policies.
- Loss of use - hotel or rental costs if your home is temporarily uninhabitable.
One detail that surprises people: the "access" coverage is often capped. A policy might pay $5,000 toward slab demolition and restoration even when the pipe repair itself is on you. Read that sublimit before you assume you're fully covered.
If you're not sure whether your policy responds, our team can help document the damage. We handle water leak detection Missouri City and provide the written findings your adjuster will ask for.
What Insurance Usually Won't Cover for Slab Leaks
Is slab leak covered by insurance Texas homeowners ask about most often - and the honest answer is that the pipe repair almost never is. Insurers treat the plumbing line itself as a maintenance item, the same way they treat a worn-out water heater or a failing AC compressor.
What's typically excluded:
- The pipe repair itself - cutting out and replacing the failed section of copper or PEX.
- Gradual leaks - pinhole leaks, corrosion, and slow weeping that developed over months.
- Poor installation or defective materials - if the original plumbing was done wrong.
- Freeze damage - unless you can show you maintained heat and the event was truly sudden.
- Foundation cracks - unless they're directly tied to a covered peril like a burst pipe.
We've walked hundreds of Missouri City slabs, and the pattern is consistent: the older the home, the more likely the adjuster calls it wear and tear. Homes in Slab Leak Repair in Sienna built in the 1990s and early 2000s are now hitting the age where original copper lines are failing, and those claims almost always land in the excluded bucket.
That doesn't mean you're stuck paying full price. It means you need a repair strategy that fits the reality of your coverage - and sometimes that's a trenchless fix that costs far less than tearing up the whole floor.
How to File a Slab Leak Claim in Missouri City
How to file a slab leak claim in Missouri City comes down to documentation and timing. The stronger your evidence that the damage was sudden and accidental, the better your odds. Here's the sequence that works:
- Stop the water. Shut off the main valve and call a licensed plumber to confirm the leak location. You can't file a credible claim without knowing where the water is coming from.
- Document everything. Photos of wet flooring, warped baseboards, and standing water. Keep the damaged materials until the adjuster sees them.
- Get a written leak report. A plumber's report identifying the leak location, cause, and whether it was sudden or gradual carries real weight.
- Call your insurer promptly. Most policies require notice within a reasonable time - days, not weeks. Delay is one of the most common reasons claims get denied.
- Separate the pipe repair from the damage claim. Tell your adjuster upfront that you understand the pipe may be excluded but the water damage is what you're claiming.
- Keep every receipt. Emergency plumber visits, hotel stays, and mitigation costs all count.
One thing to know before you start: your deductible applies. If your water damage is $4,000 and your deductible is $3,500, you're filing a claim for $500 - and that claim still goes on your loss history. Sometimes it's smarter to pay out of pocket.
Common Mistakes That Get Slab Leak Claims Denied
The most common mistake we see is homeowners waiting too long to act. A slab leak that's been running for weeks gives the adjuster an easy argument that the damage was gradual and preventable.
Other claim-killers:
- Doing the repair before the adjuster sees it. Once the pipe is replaced and the slab is patched, the evidence is gone.
- Describing it as "been leaking a while." That phrase alone can sink a claim. Stick to what you observed and when.
- No professional leak report. A plumber's written findings are the difference between a paid claim and a denied one.
- Filing for a repair that's clearly maintenance. A 30-year-old copper line that corroded is not a covered peril, and filing anyway can flag your policy.
- Ignoring the policy sublimits. Assuming full coverage for slab access when your policy caps it at $5,000 leads to an ugly surprise.
We've seen homeowners in Lake Olympia Slab Leak Repair lose legitimate damage claims simply because they tore out the wet flooring before documenting it. Take the photos first. Always.
When to Call a Professional
Call a professional the moment you notice warm spots on the floor, the sound of running water when nothing is on, or a water bill that jumped by $80 or more in a single month. Those are the three classic slab leak signals, and they don't fix themselves.
Our team at Missouri City Slab Leak Repair locates the leak with acoustic listening equipment and thermal imaging, then gives you a written report you can hand straight to your adjuster. We handle the repair - whether that's a spot fix, a slab leak tunneling Missouri City TX approach that avoids tearing up your whole floor, or a full reroute. You get a dry slab and clean documentation.
If you're dealing with a high water bill and no visible leak, start with a professional investigation before you call your insurer. You need to know what you're claiming before you file.
Frequently Asked Questions
Does homeowners insurance cover slab leaks in Missouri City TX?
Rarely for the pipe repair itself. Most Texas policies exclude slab leaks caused by corrosion, age, or wear and tear. The water damage the leak causes - flooring, walls, personal property - is often covered if the loss was sudden and accidental. Check your policy's specific exclusions.
How do I file a slab leak insurance claim in Missouri City?
Shut off the water, get a licensed plumber to document the leak in writing, photograph all damage, then call your insurer within days. Keep damaged materials until the adjuster inspects. File the water damage claim separately from the pipe repair, since the pipe is usually excluded.
What is covered for slab leaks in Missouri City Texas?
Typically the resulting water damage: soaked flooring, baseboards, drywall, personal belongings, and sometimes the cost of breaking out and restoring the slab to access the leak. Many policies cap access coverage around $5,000. The pipe repair itself is usually your responsibility.
Will insurance pay for slab leak repair in Missouri City?
Usually no, unless the leak was caused by a sudden covered event like a burst pipe from freezing or contractor damage. Gradual leaks from old copper or PEX lines are classified as maintenance and excluded. You'll likely pay for the pipe repair out of pocket.
How much does slab leak repair cost in Missouri City in 2026?
Typical 2026 pricing in this area runs $1,500 to $4,500 for a spot repair, $6,000 to $12,000 for tunneling access, and $8,000 to $15,000 for a full pipe reroute. Whole-house repiping can exceed $15,000. Insurance rarely covers these pipe costs.
Get Help with Slab Leak Repair in Missouri City
Whether your claim gets approved or you're paying out of pocket, the repair still has to happen - and fast, before the water damage spreads. We locate, document, and fix slab leaks across Missouri City and the surrounding communities.
Call Missouri City Slab Leak Repair at (281) 326-6169 for same-day leak detection and a written report you can hand to your insurance adjuster.